Work out what’s realistic
We’ll look at your income, commitments, deposit and credit history to understand a sensible budget.
Deposits, affordability, credit scores, Agreements in Principle… it can feel like everyone speaks fluent mortgage except you. I’ll explain it properly, compare mortgages from across the market and help you from your first question through to the full application.
 Still me—just illustrated! 👋
I’ll turn the mortgage maze into a clear, manageable plan.
We’ll look at your income, commitments, deposit and credit history to understand a sensible budget.
I compare mortgages from across the market—including lenders that may take a different view of past credit problems.
I’ll help with your Agreement in Principle, paperwork and full application, keeping you updated along the way.
No secret handshake required. Here’s what normally happens.
Tell me where you are now and what you’re hoping to buy.
We look at affordability, deposit and likely costs.
I help you apply so you can house-hunt with more confidence.
I compare suitable mortgages and recommend an option.
I submit it and support you through to the mortgage offer.
There are no silly questions—especially when you’re making one of the biggest decisions of your life.
A missed payment, default, CCJ or debt management plan can make things more complicated—but complicated is not the same as impossible.
Different lenders look at credit problems in different ways. The type, amount, age and current status can all matter. I’ll look at the full picture, explain what may be realistic and avoid firing off applications without a plan.
No judgement. No lecture. Just a proper look at your options.
Every case is different, but these are the sorts of conversations I regularly help with.
A first-time buyer has a satisfied default from a difficult period a few years ago and assumes every lender will say no.
How I help: check the detail, identify lenders whose criteria may fit and explain the likely deposit and evidence needed.
A couple have maintained their DMP payments and saved a deposit but don’t know whether home ownership is realistic yet.
How I help: review the timing, affordability and lender criteria, then give them an honest plan—even if the best next step is to wait.
A buyer worries that the combination rules them out completely.
How I help: consider the CCJ’s age, value and status alongside the deposit, income and wider credit file before approaching a suitable lender.
A couple are unsure how existing monthly commitments affect what they can borrow.
How I help: calculate a sensible range, explain the affordability impact and compare suitable options.
A buyer has left employment to start a business and assumes they must wait years before applying.
How I help: understand their history, available accounts and evidence, then check which lender approaches may be relevant.
A buyer has found a home but feels lost between estate agents, solicitors, surveys and lenders.
How I help: manage the mortgage side, explain each stage plainly and keep the application moving.
These are illustrative situations, not guarantees of mortgage availability. Eligibility depends on individual circumstances and lender criteria.
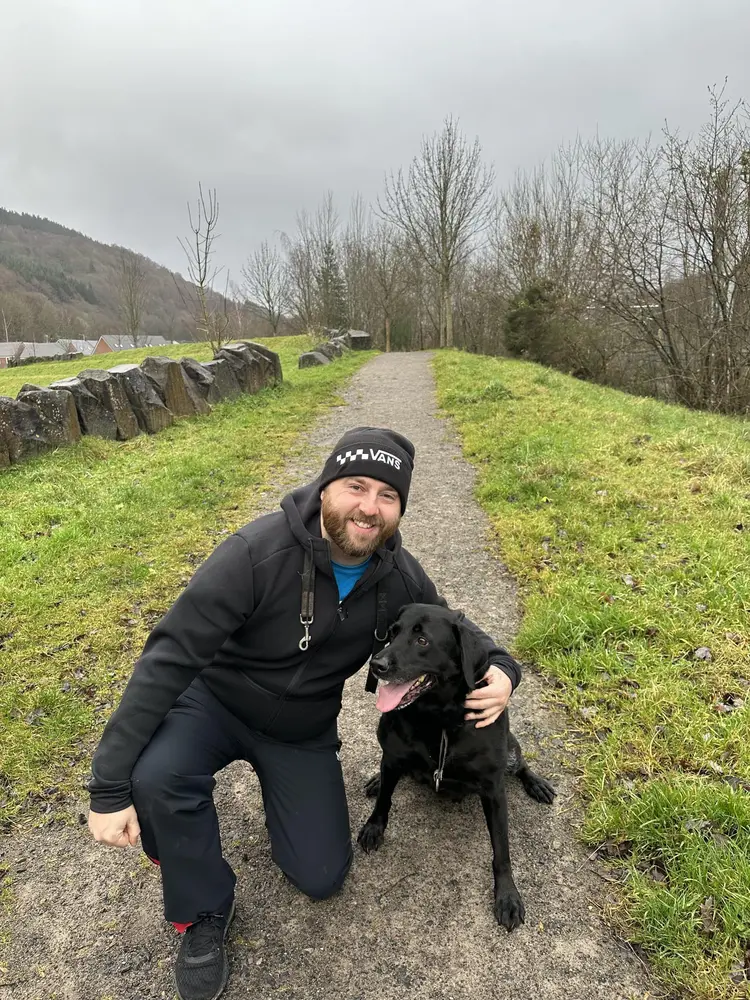
I’m a qualified mortgage and protection adviser with over 10 years’ experience. I’m based in South Wales and help clients across the UK by phone.
Buying your first home is exciting, but the mortgage bit can feel like a test nobody gave you the revision notes for. My job is to make it clearer, answer the questions you’re worried are “silly” and help you make confident decisions.
When I’m not working, you’ll normally find me mountain biking, following Formula 1, walking Sully or losing golf balls somewhere I was definitely aiming for.
Tell me where you’re at—whether you’re ready to apply, just starting to save or worried about something on your credit file. We’ll work out the next sensible step together.
Booking calendar coming next—this button is ready for your new link.Some circumstances need more than a quick online calculator. These are two areas where the right lender knowledge can make a real difference.
Some first-time buyers may be able to purchase with a deposit of £5,000, rather than finding 5% of the property price. I can check whether you meet the lender’s criteria and explain the full costs and options clearly.
I help people living and working in the UK on a Skilled Worker visa understand which lenders may consider them, including how visa length, time in the UK, deposit and employment can affect the options.
Mortgage availability is subject to individual circumstances, affordability and lender criteria.